
Imagine two people.
Both earn $200,000 a year.
Both invest regularly.
Both have similar opportunities to build wealth.
But ten years later, their financial lives look completely different.
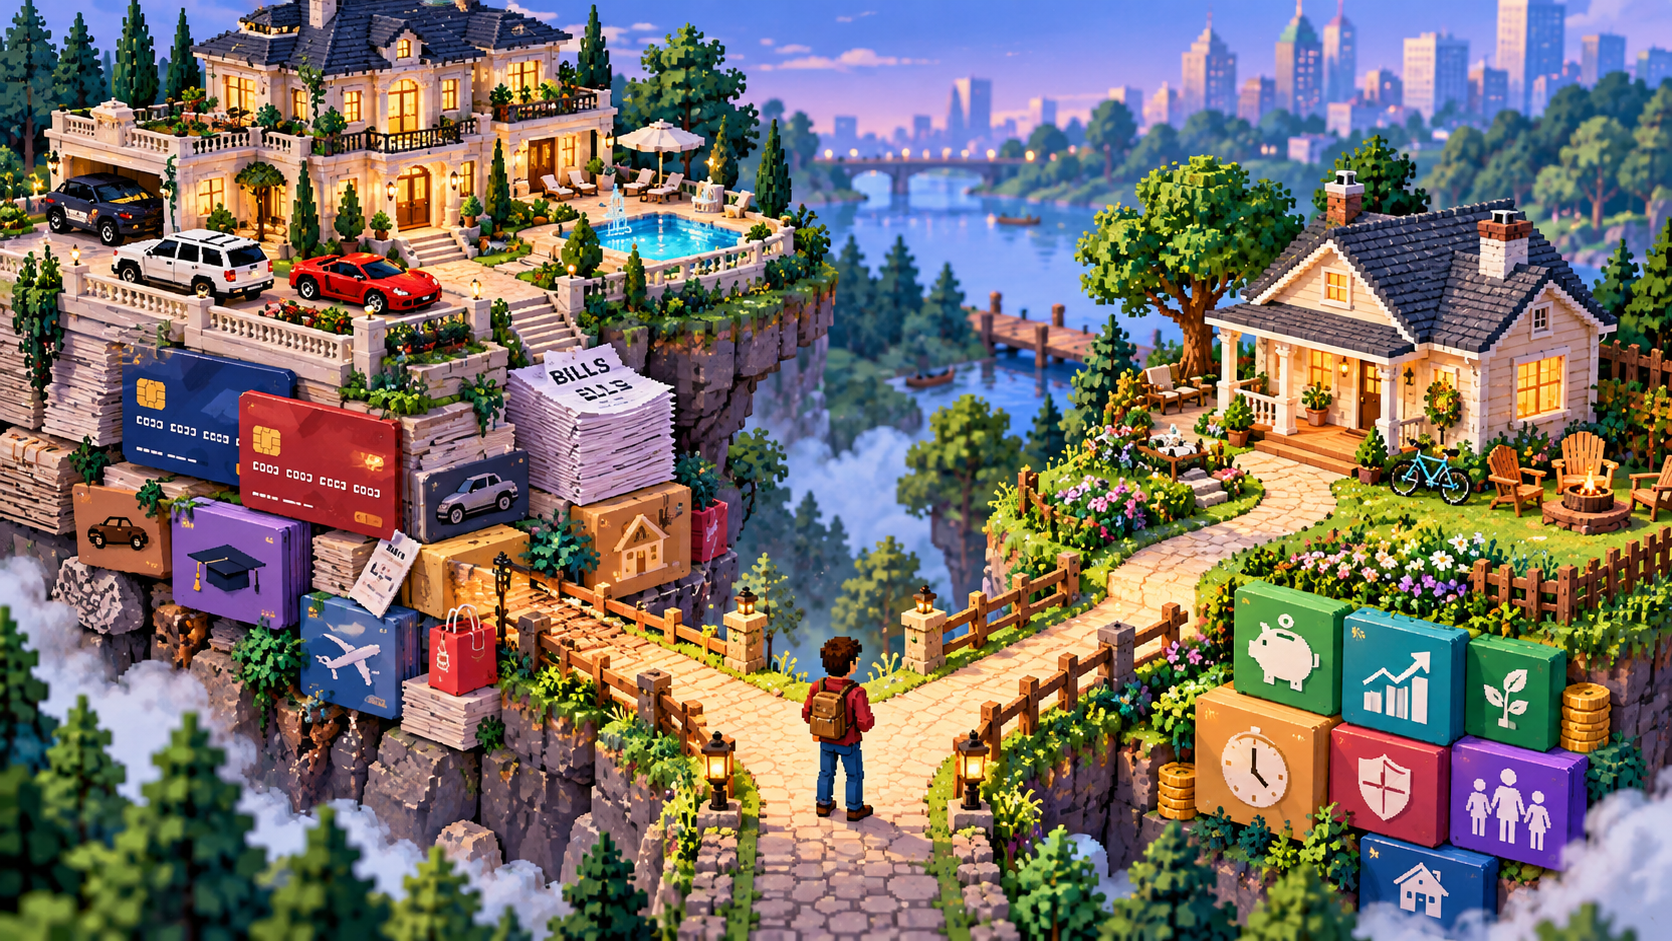
One has a comfortable investment portfolio, manageable expenses, and the flexibility to make decisions without constantly worrying about money.
The other earns more than ever but feels financially trapped.
Their house is expensive.
Their vehicles are expensive.
Their lifestyle requires a significant monthly income.
And despite years of impressive earnings, they feel as though they can’t afford to slow down.
What happened?
It probably wasn’t just a difference in investment performance.
It was the accumulation of hundreds of financial decisions made along the way.
Because here’s something we don’t discuss enough:
Building wealth isn’t only about how well you invest your money. It’s also about how much of your life your money requires you to maintain.
The Financial Advice Everyone Wants to Hear
Most people enjoy talking about investments.
Which stocks are performing well?
What’s the next big opportunity?
Should you invest in real estate?
Are index funds better than individual stocks?
How much could your portfolio grow over the next decade?
These are interesting questions.
And investing is an important part of long-term financial planning.
But investing receives so much attention that we sometimes overlook the decisions happening outside our brokerage accounts.
The house we purchase.
The vehicles we finance.
The subscriptions we accumulate.
The debt we carry.
The lifestyle we gradually become accustomed to.
The financial commitments we make without considering how difficult they may be to reverse.
These decisions may not be exciting.
But they can shape our financial future just as much as the investments we choose.
The Difference Between Being Wealthy and Looking Wealthy
There’s an important distinction between having money and appearing to have money.
A beautiful house doesn’t necessarily indicate financial security.
Neither does an expensive vehicle.
A luxury vacation.
A designer wardrobe.
Or a high income.
Those things may reflect genuine wealth.
But they can also reflect substantial financial obligations.
Consider someone earning $300,000 annually.
That’s a significant income.
But imagine they have a large mortgage, multiple vehicle payments, private school tuition, expensive memberships, and considerable credit card balances.
Their lifestyle may look impressive.
Yet their monthly expenses could consume nearly everything they earn.
Now imagine someone earning considerably less who maintains a manageable lifestyle, avoids unnecessary debt, and consistently saves and invests.
Their financial position may be stronger than appearances suggest.
Financial freedom isn’t determined by how expensive your life looks. It’s influenced by how much control you have over your money and your time.
Every Lifestyle Upgrade Creates a New Baseline
Think about the first vehicle you owned.
Maybe it was old.
Maybe it wasn’t particularly attractive.
Maybe the air conditioning worked only when it felt like cooperating.
But it got you where you needed to go.
Eventually, you purchased something nicer.
Then something nicer again.
And over time, the things that once felt luxurious began to feel normal.
The same thing happens with houses.
Vacations.
Restaurants.
Clothing.
Entertainment.
And everyday conveniences.
Psychologists often refer to our tendency to adjust to improved circumstances as hedonic adaptation.
Something that initially feels exciting can eventually become part of our normal expectations.
That’s not necessarily a problem.
Enjoying the rewards of your hard work is reasonable.
But when every increase in income leads to an increase in spending, financial flexibility may never improve.
You earn more.
You spend more.
And you still feel like you need to keep earning at the same pace.
The Hidden Cost of a More Expensive Life
Imagine your household requires $8,000 per month to maintain its lifestyle.
That’s $96,000 annually.
Now imagine your expenses gradually increase to $15,000 per month.
That’s $180,000 annually.
The difference is $84,000 every year.
Over ten years, that’s $840,000 in additional spending before accounting for inflation or any investment returns you might otherwise have earned.
Of course, some of those expenses may provide genuine value.
A larger home may better accommodate your family.
Educational expenses may support your children’s needs.
Travel may create meaningful memories.
The goal isn’t to criticize spending.
It’s to recognize that lifestyle decisions have long-term consequences.
And those consequences can influence how much freedom your money eventually provides.
Your Financial Freedom Number Depends on Your Expenses
When people discuss retirement, they often focus on how much money they need to accumulate.
One million dollars.
Three million.
Five million.
Ten million.
But the amount required depends heavily on how much you plan to spend.
Consider two households.
Household A expects to spend $80,000 annually in retirement.
Household B expects to spend $200,000 annually.
Their investment needs will be very different.
Using a hypothetical initial withdrawal rate of 4% for illustration, $80,000 in annual portfolio withdrawals corresponds to approximately $2 million in investments.
At the same rate, $200,000 corresponds to approximately $5 million.
That’s a $3 million difference.
And it exists primarily because of spending.
These figures are not guarantees or personalized retirement recommendations. Actual retirement planning must consider taxes, inflation, investment performance, retirement length, Social Security, healthcare expenses, and the possibility of adjusting withdrawals.
Still, the example illustrates an important principle:
The less expensive your lifestyle is to maintain, the less money you may need to achieve a particular level of financial independence.
Debt Can Quietly Reduce Your Choices
Not all debt is inherently bad.
A mortgage may help someone purchase a home.
Business financing may support a profitable expansion.
Certain loans may help fund education or other long-term goals.
But debt creates obligations.
And obligations reduce flexibility.
Imagine having a substantial investment portfolio but also carrying large monthly debt payments.
You might technically have significant wealth.
Yet your cash flow could still feel constrained.
Now imagine eliminating some of those payments.
Your required monthly income decreases.
Your financial breathing room increases.
You may have more flexibility to change careers, reduce working hours, or handle unexpected expenses.
Paying down debt isn’t always the mathematically superior choice compared with investing.
Interest rates, taxes, liquidity, and investment risk matter.
But the value of lower required payments deserves consideration.
Sometimes reducing financial obligations is about more than saving interest.
It’s about creating options.
The Danger of Building a Lifestyle Around Your Best Year
This is especially important for business owners, commissioned professionals, and anyone whose income fluctuates.
Imagine having an exceptionally profitable year.
Business is booming.
Revenue is strong.
Bonuses are higher than expected.
Investments have performed well.
It feels as though your financial situation has permanently improved.
So you make permanent spending decisions.
A larger house.
More expensive vehicles.
Additional recurring expenses.
Perhaps another property.
But what happens if income declines?
A strong year doesn’t guarantee that every future year will be equally strong.
Economic conditions change.
Businesses experience fluctuations.
Unexpected expenses arise.
Markets decline.
A lifestyle built around peak income can become stressful when circumstances return to normal.
A more sustainable approach is to distinguish between recurring income and unusually strong financial years.
Enjoy success.
Celebrate milestones.
But be cautious about turning temporary increases in income into permanent obligations.
The Emergency Fund Nobody Wants to Talk About
Emergency savings aren’t exciting.
They don’t generate impressive headlines.
They don’t promise extraordinary returns.
They don’t make for particularly interesting dinner conversations.
But they serve an important purpose.
An emergency fund can help protect you from unexpected expenses without forcing you to sell long-term investments at an unfavorable time or rely on expensive debt.
A major home repair.
An unexpected medical bill.
A temporary interruption in income.
An urgent family expense.
These situations become easier to manage when you have accessible reserves.
The appropriate amount depends on your circumstances.
Someone with stable employment and relatively predictable expenses may have different needs than a business owner whose income varies significantly.
The goal isn’t to keep every dollar in cash.
It’s to ensure that short-term financial needs don’t unnecessarily disrupt long-term plans.
The Financial Value of Saying No
We often associate wealth building with saying yes.
Yes to opportunities.
Yes to investments.
Yes to expansion.
Yes to new experiences.
But financial discipline also requires knowing when to say no.
No to a purchase that doesn’t provide enough value.
No to a financial commitment that creates unnecessary pressure.
No to an investment you don’t understand.
No to a lifestyle upgrade that doesn’t align with your priorities.
No to taking on another responsibility simply because you can afford it.
Sometimes the most financially valuable decision is the opportunity you decline.
Not because you’re afraid to spend money.
But because you understand what matters most.
You Don’t Have to Maximize Every Dollar
There’s another side to this conversation.
Being financially responsible doesn’t mean refusing to enjoy your money.
You don’t need to turn every purchase into a mathematical calculation.
You don’t need to feel guilty about vacations.
You don’t need to drive an old vehicle forever.
You don’t need to avoid every restaurant or luxury.
Money is supposed to serve your life.
The goal isn’t to accumulate the largest possible number while denying yourself every enjoyable experience.
It’s to spend intentionally.
Perhaps travel is incredibly important to your family.
Maybe you love boating.
Maybe you enjoy a beautiful home.
Maybe dining out with friends brings you genuine happiness.
Those things can be worthwhile.
The question isn’t whether a purchase is necessary.
It’s whether it provides enough value to justify its cost within your financial plan.
The Difference Between a Purchase and a Commitment
Some expenses happen once.
Others follow you for years.
Buying a television is generally a one-time purchase.
Buying a larger house can create decades of additional expenses.
A new vehicle may come with monthly payments, higher insurance premiums, and maintenance costs.
A second property may require taxes, insurance, repairs, and ongoing management.
A membership may renew automatically every month.
These commitments deserve special attention because they affect future cash flow.
Before taking on a major recurring expense, ask:
Would I still feel comfortable with this payment if my income declined?
Does this purchase improve my life enough to justify the ongoing cost?
Will this obligation limit opportunities I may want later?
Could I comfortably maintain it without sacrificing my long-term goals?
The answers may help you avoid commitments that become burdens.
Wealth Should Eventually Make Life Easier
Imagine spending thirty years building wealth.
You work hard.
Take risks.
Make sacrifices.
Invest consistently.
And eventually accumulate substantial assets.
But you’re still constantly stressed.
Still overcommitted.
Still worried about maintaining your lifestyle.
Still unable to step away from work.
Still feeling obligated to pursue every financial opportunity.
At some point, it’s worth asking:
What was all that effort supposed to accomplish?
For many people, the purpose of wealth is security.
Flexibility.
Time with family.
The ability to make choices.
The opportunity to pursue meaningful experiences.
The freedom to stop doing certain things simply because you need the money.
If building wealth creates increasingly complicated obligations without improving your quality of life, it may be time to reconsider how you’re measuring success.
Financial Independence Is About Choices
Financial independence doesn’t necessarily mean never working again.
Some people love their careers.
Others enjoy operating businesses.
Some find purpose in building companies or managing investments.
Financial independence can mean continuing to work because you want to.
Not because every monthly payment depends on it.
It can mean choosing projects that interest you.
Taking time away when needed.
Spending more time with family.
Supporting causes you care about.
Or simply sleeping better because your financial life is manageable.
That kind of freedom depends on more than investment returns.
It depends on the relationship between your assets, income, expenses, and obligations.
Review the Expenses That Became Automatic
Here’s a useful exercise.
Look at your monthly spending.
Not just the obvious expenses.
Look at everything.
Streaming services.
Memberships.
Insurance premiums.
Subscriptions.
Financing payments.
Recurring purchases.
Services you no longer use.
Expenses that increased gradually without much attention.
You may discover that some are still valuable.
Keep those.
But others may no longer serve a meaningful purpose.
Canceling a few subscriptions probably won’t transform your financial future overnight.
But reviewing automatic spending can help you develop a more intentional relationship with money.
And sometimes the biggest opportunities involve much larger recurring commitments.
Protect Your Ability to Change Direction
Life rarely unfolds exactly as planned.
Your priorities at thirty may differ from your priorities at fifty.
A career you once loved may become less appealing.
A business you built may no longer fit your goals.
Your family circumstances may change.
Your health may change.
You may discover new interests.
Financial flexibility gives you room to respond.
But flexibility becomes harder when every dollar of income is already committed.
That’s why maintaining manageable expenses, appropriate savings, and a thoughtful investment strategy matters.
You’re not simply preparing for retirement.
You’re preparing for the possibility that your life may evolve.
The Five Financial Questions Worth Asking
Before making another major financial commitment, consider these questions.
1. Does this improve my life in a meaningful way?
Not whether other people will be impressed.
Whether it genuinely matters to you.
2. What will this cost beyond the purchase price?
Include maintenance, insurance, taxes, financing, and ongoing responsibilities.
3. How does this affect my future flexibility?
Will it make changing careers, reducing work, or pursuing another opportunity more difficult?
4. Can I comfortably afford it during a less profitable year?
Don’t assume your best financial circumstances will continue indefinitely.
5. Would I still choose this if nobody else knew I owned it?
That final question can reveal whether a purchase reflects personal enjoyment or outside expectations.
You Can Be Successful Without Constantly Upgrading
One of the most freeing financial realizations is that you don’t have to increase your lifestyle every time your income increases.
You can earn more and keep driving the same vehicle.
You can build wealth without buying a larger house.
You can enjoy success without making every purchase more expensive.
You can invest additional income.
Pay down debt.
Build reserves.
Create opportunities.
Or spend more intentionally on experiences that matter.
There’s no requirement that your expenses grow alongside your earnings.
And choosing not to upgrade doesn’t mean you’re missing out.
Sometimes it means you’re choosing a different kind of reward.
What Does Enough Look Like?
This may be the most important question of all.
How much is enough?
Enough income.
Enough savings.
Enough investments.
Enough property.
Enough possessions.
Enough financial security.
The answer is different for everyone.
And it may change over time.
But without some understanding of what enough looks like, financial goals can become endless.
Every milestone creates another.
Every achievement leads to a larger target.
And the opportunity to enjoy what you’ve built keeps getting pushed further into the future.
Defining enough doesn’t mean abandoning ambition.
It means giving ambition a purpose.
The Real Financial Goal
A successful financial life isn’t necessarily the one with the highest investment return.
Or the most properties.
Or the largest business.
Or the most impressive lifestyle.
It’s one in which your financial decisions support the life you want to live.
That includes investing wisely.
But it also includes spending thoughtfully.
Managing debt.
Maintaining appropriate savings.
Understanding risk.
Protecting your family.
And avoiding obligations that unnecessarily limit your choices.
Because the purpose of building wealth isn’t simply to own more things.
It’s to create greater control over your future.
You can make excellent investments and still struggle financially if the rest of your money isn’t working toward the life you want.
So yes, pay attention to your investments.
Understand your portfolio.
Think about long-term growth.
But don’t overlook the everyday financial decisions happening outside your brokerage account.
Those choices may ultimately determine how much freedom your wealth provides.
🌱 The Daily Vine
💭 Today’s Thought
“Building wealth isn’t only about how well you invest your money. It’s also about how much of your life your money requires you to maintain.”
📚 Book Recommendation
The Psychology of Money — Morgan Housel
An accessible exploration of how behavior, expectations, risk, and personal values influence financial success.
🎯 Today’s Challenge
Review your five largest recurring household expenses.
Ask whether each one still provides enough value to justify its cost.
💰 Money Minute
A $500 monthly expense equals $6,000 annually.
Over ten years, that’s $60,000 in spending before considering inflation or the potential investment growth of money saved instead.
Small recurring decisions can have meaningful long-term consequences.
❤️ Relationship Reminder
Discuss major financial decisions with your spouse or partner before making commitments that affect your shared future.
Financial alignment isn’t about agreeing on every purchase. It’s about understanding priorities and making important decisions together.
🙏 Gratitude Prompt
What’s something you already own or experience that once felt like a major financial goal?
Take a moment to appreciate it before focusing on the next milestone.
🌿 Grow Today
Identify one area where you’ve allowed your lifestyle to become more expensive without a meaningful improvement in happiness or convenience.
Consider whether simplifying it would create greater financial flexibility.
💰 The Compound Corner
One Wealth Habit: Review Your Fixed Expenses
Once each quarter, review the recurring costs that determine how much income your household needs.
Focus especially on major expenses such as housing, transportation, insurance, debt payments, and ongoing services.
One Investing Lesson: Returns Aren’t Everything
Investment performance matters, but long-term financial security also depends on your savings rate, spending needs, asset allocation, taxes, fees, and ability to remain invested through market fluctuations.
A portfolio should support your financial goals—not become the only measure of success.
One Financial Term: Lifestyle Inflation
Lifestyle inflation occurs when spending increases as income rises.
It isn’t inherently harmful. The concern arises when higher spending prevents meaningful improvements in savings, financial security, or flexibility.
Wealth & Wisdom Tuesday Question
If your income suddenly dropped by 25%, which parts of your current lifestyle would create the most financial pressure—and what could you change today to reduce that risk?
📚 Recommended Resources
- The Psychology of Money — Morgan Housel https://link.amazon/B07SMGmhr
- Your Money or Your Life — Vicki Robin and Joe Dominguez https://link.amazon/B06CgKlwS
- The Millionaire Next Door — Thomas J. Stanley and William D. Danko https://link.amazon/B0adljUra
- Die With Zero — Bill Perkins https://link.amazon/B0dzHuElc
- The Simple Path to Wealth — JL Collins https://link.amazon/B05mmb2Yp
Affiliate disclosure: Some recommended resources may contain affiliate links when published. SproutVine may earn a commission from qualifying purchases at no additional cost to readers.
Financial disclaimer: This article is intended for general educational purposes and should not be considered personalized investment, financial, tax, or legal advice.
❓ Frequently Asked Questions (FAQ)
1. What financial decisions have the biggest impact on building wealth?
Some of the most important financial decisions involve how much you save, how much debt you carry, your housing and transportation costs, how consistently you invest, and whether your lifestyle remains affordable as your income changes. These decisions can have a significant impact on your long-term financial flexibility.
2. Is saving money more important than investing?
Both play important roles. Saving helps provide liquidity for emergencies and short-term needs, while investing offers the potential for long-term growth. The appropriate balance depends on your financial goals, time horizon, and risk tolerance.
3. What is lifestyle inflation, and why can it be harmful?
Lifestyle inflation occurs when spending rises alongside income. It becomes problematic when increased expenses prevent someone from saving, investing, reducing debt, or improving financial security. Higher spending isn’t automatically harmful, but it should reflect intentional priorities.
4. How much money do I need to become financially independent?
The amount depends on your expected expenses, investment portfolio, other income sources, taxes, retirement timeline, and risk tolerance. Someone who needs $80,000 annually may require a substantially different financial plan than someone who needs $200,000.
5. Should I pay off debt or invest my extra money?
That depends on factors such as the debt’s interest rate, available emergency savings, potential investment returns, taxes, and personal risk tolerance. High-interest debt often deserves particular attention because its cost is relatively predictable, while investment returns are uncertain.
6. How can I avoid lifestyle inflation as my income increases?
Consider allocating part of each raise or income increase toward savings, investments, or debt reduction before expanding recurring expenses. You can still enjoy financial success while ensuring that higher earnings improve your long-term flexibility.
7. Can someone with a high income still struggle financially?
Absolutely. A high income doesn’t guarantee financial security. Large recurring expenses, substantial debt, inadequate savings, and unpredictable income can create financial pressure even for households earning significant amounts of money.
8. What is the difference between being wealthy and being financially independent?
Wealth generally refers to accumulated assets and net worth. Financial independence refers to having sufficient resources or reliable income to support your lifestyle without depending entirely on ongoing employment. Someone can have substantial assets but still face cash-flow constraints or significant financial obligations.
🌱 Today’s SproutVine Takeaway
The ultimate goal of building wealth isn’t to afford an increasingly expensive life. It’s to create a life where money gives you more choices, less pressure, and greater freedom.